
Fintech & Payments
Kamal Prabhakar of Transact World Group Awarded Rising Payment Service Provider at Rising Bharat Conclave in UK Parliament

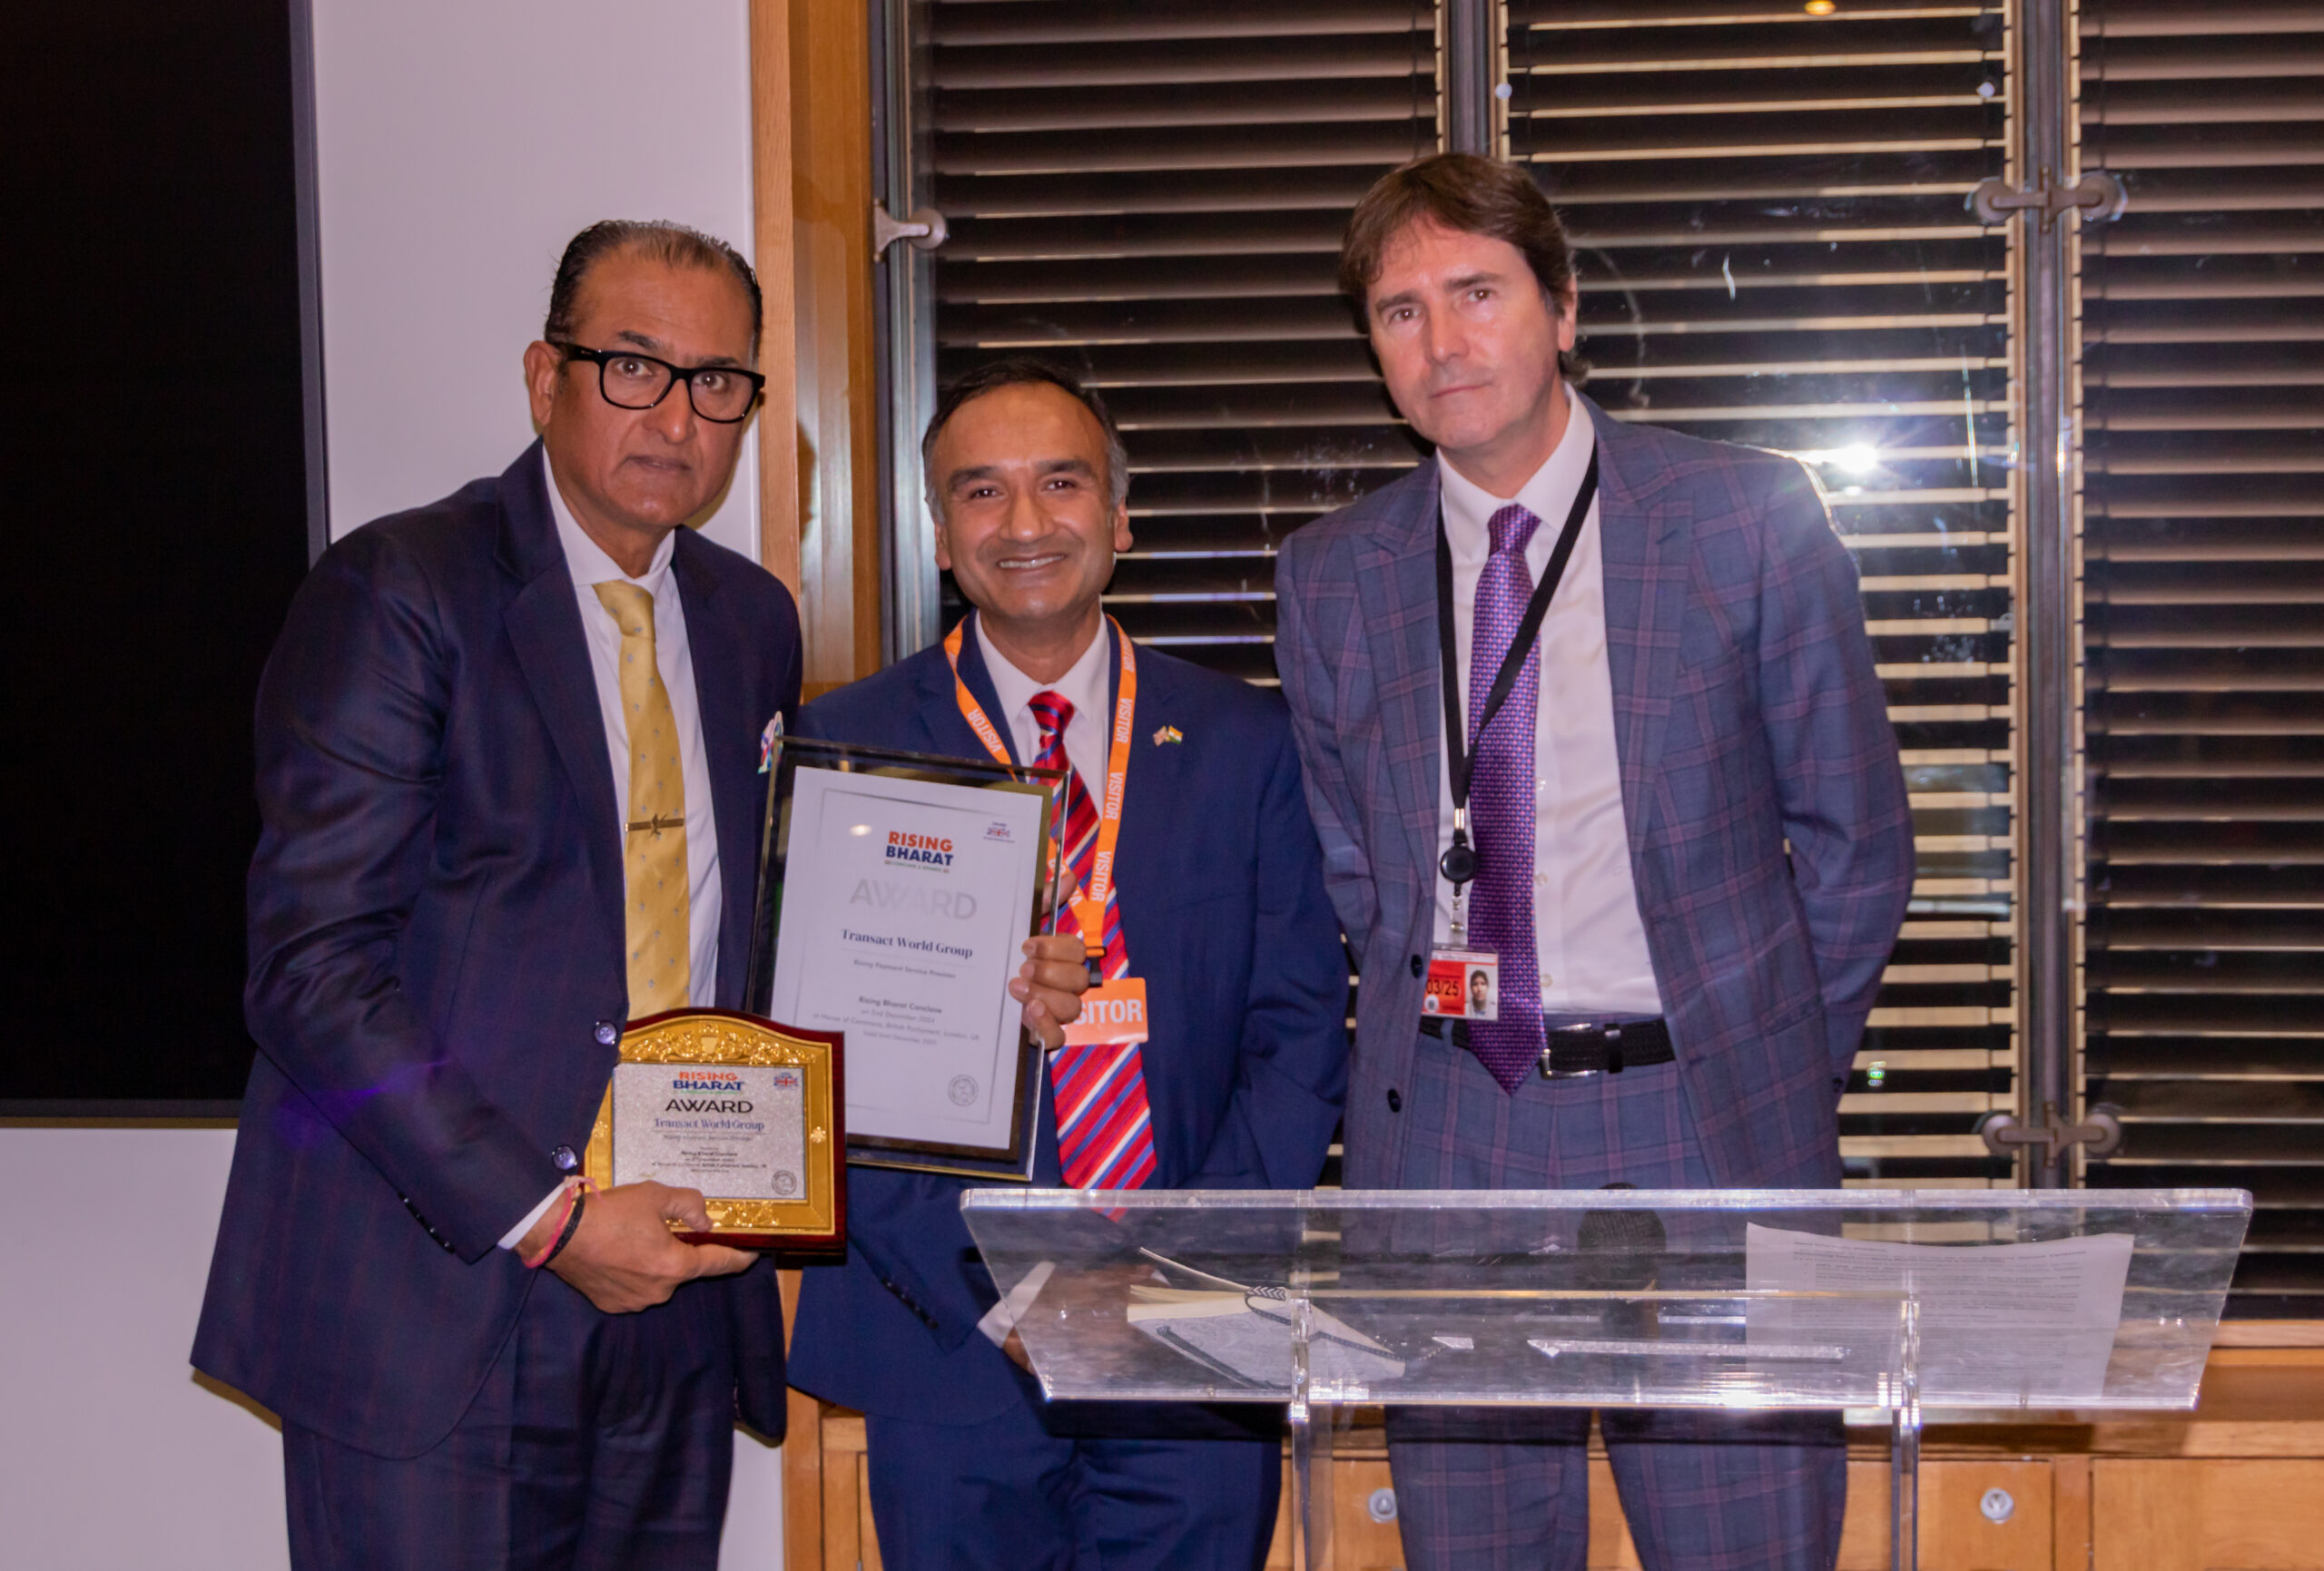
Kamal Prabhakar, of Transact World Group, was honored with the Rising Payment Service Provider Award at the Rising Bharat Conclave and Award Ceremony, held at the House of Commons in the UK Parliament on December 2, 2024. The award recognized Prabhakar’s leadership and his company’s pioneering contributions to the global payments industry. Under his stewardship, Transact World Group has revolutionized digital payments, helping businesses and consumers across the world access secure and efficient financial solutions.
The Conclave was graced by a distinguished gathering of dignitaries, including representatives from 14 embassies and high commissions, former Chief Ministers, ex-MEPs, and influential business leaders from India, Poland, Turkey, and the UAE. Notable attendees included Stanley Johnson, CEO of Upcycled Plastics Ltd.; John Le Fondré A.C.A., former Chief Minister of Jersey; Andrew Grocock, Chief of Staff to Baroness Arlene Foster; and Graham Cook, Country Manager at Air India. Their participation underscored the event’s importance in strengthening international ties and fostering collaboration between the UK and India.
A significant highlight of the event was the letter of appreciation received from 10 Downing Street, commending the Conclave’s efforts to enhance UK-India relations.
In inaugural speech, Sudeep Sakalle emphasized the importance of sharing success stories and the strength of the UKABC community. Dr. Madhur Temle also presented a compelling vision for India’s future ahead of its centenary of independence in 2047.
The Conclave also featured insightful discussions on the UK-India Free Trade Agreement (FTA), with Neil Lal, President of the India Council of Scotland, highlighting its potential to create jobs and foster mutual economic growth.
Hosted by Taha Coburn-Kutay, Chairman of UKABC, the event marked a milestone in UK-India relations, setting the stage for future collaborations that will drive innovation and economic prosperity for both nations.

Explainers
Card Processing Fees in the UK: A Plain-English Guide for Small Businesses
Every card payment carries a fee — but few business owners know what they are actually paying for. Here is how UK card processing fees work, what is capped, and how to keep costs under control.


In short: A UK card fee is made up of three parts — interchange (paid to the cardholder’s bank), scheme fees (paid to Visa or Mastercard) and the acquirer’s margin (paid to your payment provider). Interchange on UK consumer cards is capped at 0.2% for debit and 0.3% for credit, but business cards and many international cards are not capped — which is where costs often creep up.
For most small businesses, card payments are no longer optional. Customers expect to tap, click or pay by phone. But the monthly statement from a payment provider can be hard to read, and many owners only discover what they are paying when margins start to feel tight. Understanding the structure is the first step to paying less.
What makes up a card processing fee?
- Interchange: the largest part, paid to the bank that issued the customer’s card. For UK consumer cards it is capped by regulation at 0.2% of the transaction for debit and 0.3% for credit.
- Scheme fees: charged by the card networks for using their rails. They vary by card type, transaction type and region.
- Acquirer margin: what your payment provider charges for processing, settlement, risk and support. This is the part you can negotiate.
Which card payments cost more?
The caps only apply to UK consumer cards. Commercial and corporate cards are not capped, and interchange on some cross-border payments can be considerably higher. Online, or “card-not-present”, payments also tend to cost more than in-person transactions because the fraud risk is higher. A business with many corporate customers or international buyers can therefore pay far more than the headline rate suggests.
Blended pricing or Interchange++?
Providers usually price in one of two ways. Blended (flat-rate) pricing charges one simple percentage on everything — easy to understand, but you may overpay on cheap debit transactions. Interchange++ passes through the actual interchange and scheme fees and adds a clear margin on top — more complex to read, but usually fairer for businesses with steady volumes.
How can a small business reduce card fees?
- Know your card mix. Ask your provider for a breakdown of debit, credit, commercial and international transactions. Your mix decides which pricing model suits you.
- Check the “hidden” lines. Monthly minimums, terminal rental, PCI compliance charges, refund fees and chargeback fees all add up.
- Benchmark once a year. As volumes grow, your negotiating position improves. A short review can unlock better rates.
- Reduce chargebacks. Clear descriptors on statements, good receipts and strong fraud tools cut disputes and their fees.
- Consider alternatives such as open banking “pay by bank” for larger or recurring payments.
What does the interchange cap mean in pounds and pence?
Percentages can feel abstract, so it helps to put numbers on them. On a £20 purchase made with a UK consumer debit card, the regulated cap means interchange can be no more than 4p (0.2%). On a £20 consumer credit card purchase, the cap is 6p (0.3%). Scheme fees and the provider’s margin then sit on top of that.
The same £20 paid with an uncapped corporate card or a card issued outside the UK can carry interchange that is several times higher. That is why two businesses with identical turnover can end up with very different card bills: the difference is usually in who their customers are and how they pay, not in the headline rate.
Can a business charge customers extra for paying by card?
Not for most everyday purchases. Since January 2018, UK businesses have been banned from adding a surcharge when consumers pay with personal debit or credit cards, and with many other common payment methods. The ban does not cover payments made with commercial or corporate cards, but any surcharge there must not exceed the actual cost to the business of accepting that card.
In practice, this means card costs have to be built into pricing rather than passed on at the till. That makes understanding and managing those costs even more important.
What should you look for in a payment provider contract?
The rate is only part of the deal. Before signing, it is worth checking:
- Contract length and exit terms — some terminal agreements run for several years and carry early termination fees.
- Terminal costs — whether card machines are bought outright, rented monthly or included.
- Settlement speed — how quickly money reaches your bank account, which matters for cash flow.
- PCI DSS requirements — the Payment Card Industry Data Security Standard sets security rules for anyone handling card data. Ask what your provider expects you to do and whether it charges a compliance fee.
- Support — what happens when a terminal fails on a busy Saturday.
Are card fees under regulatory scrutiny?
Yes. While interchange on UK consumer cards is capped, the other parts of the fee are not. The Payment Systems Regulator has examined card scheme and processing fees, and the interchange charged on online payments between the UK and the European Economic Area rose significantly after Brexit, when the old EU caps stopped applying to those transactions. Businesses selling online to European customers should keep an eye on how these rules develop, as they can have a direct effect on costs.
The bottom line
Card fees are not fixed costs — they are a commercial agreement. Businesses that understand their card mix and read their statements line by line are almost always in a position to pay less, and to choose a provider that genuinely fits how they trade.
Frequently asked questions
What is the interchange cap in the UK?
Interchange on UK consumer cards is capped at 0.2% of the transaction value for debit cards and 0.3% for credit cards. Commercial cards are not capped.
What is Interchange++ pricing?
Interchange++ passes the actual interchange and card scheme fees through to the merchant and adds a fixed, transparent margin from the payment provider.
Why are online card payments more expensive?
Card-not-present payments carry higher fraud risk, so interchange and processing costs are typically higher than for in-person contactless or chip-and-PIN payments.
Related on CWN Times: What is an electronic money institution? EMI vs bank, explained
Explainers
What Is an Electronic Money Institution? EMI vs Bank, Explained
Many business accounts and payment apps in the UK are provided by electronic money institutions, not banks. Here is what an EMI is, how your money is protected, and what to check before you choose one.

In short: An electronic money institution (EMI) is a firm authorised by the Financial Conduct Authority to issue e-money and provide payment services such as accounts, cards and transfers. Unlike a bank, an EMI cannot lend out customer money. Instead, it must safeguard it — keeping it separate from its own funds. E-money is generally not covered by the FSCS, so how a provider safeguards funds really matters.
Open a business account with a modern fintech, pay with a digital wallet or receive funds through an online payments platform, and there is a good chance the provider is an EMI rather than a bank. EMIs have transformed how small businesses move money — often faster and cheaper than traditional banking. But the way they hold your money is different, and every business owner should understand it.
What is an electronic money institution?
In the UK, EMIs are authorised and supervised by the Financial Conduct Authority (FCA) under the Electronic Money Regulations 2011. They can issue electronic money — a digital store of value in exchange for funds received — and offer payment services such as accounts with sort codes and IBANs, payment cards, domestic and international transfers, and merchant payment acceptance.
What is the difference between an EMI and a bank?
| Bank | Electronic money institution | |
|---|---|---|
| Can lend customer deposits | Yes | No |
| Pays interest on balances | Often | Not on e-money itself |
| FSCS protection (up to the limit) | Yes, for eligible deposits | Generally no |
| How customer money is protected | Capital rules and FSCS | Safeguarding, kept separate from the firm’s own money |
| Regulator | PRA and FCA | FCA |
How is money held with an EMI protected?
EMIs must safeguard customer funds, typically by holding them in a segregated account at a bank or by covering them with an insurance policy or guarantee. If the EMI fails, safeguarded funds are meant to be returned to customers ahead of the firm’s other creditors.
In practice, past failures exposed weaknesses: the FCA found that payment firms which became insolvent between 2018 and 2023 had average shortfalls of 65% of customer funds. In response, new FCA safeguarding rules — known as CASS 15 — took effect on 7 May 2026. They require daily checks that the right amount is safeguarded, monthly reporting, annual audits for firms holding more than £100,000 of customer funds, and better plans to return money quickly if a firm fails.
What should a business check before choosing an EMI?
- Check the FCA Register. Confirm the firm is authorised as an EMI (or is an agent of one) and note its firm reference number.
- Ask how funds are safeguarded — with which bank, and whether by segregation or insurance.
- Understand fees and FX. Compare transaction, currency conversion and settlement costs, not just the headline price.
- Check settlement times and limits, especially if cash flow depends on fast access to card takings.
- Don’t keep all your eggs in one basket. Many businesses use an EMI for payments alongside a bank account for reserves.
The bottom line
EMIs have brought speed, choice and lower costs to business payments, and the new safeguarding rules make the sector stronger. The key for business owners is simple: know who holds your money, how it is protected, and use the right provider for the right job.
Frequently asked questions
Is money in an EMI account protected by the FSCS?
Generally no. E-money is not covered by the Financial Services Compensation Scheme. Instead, EMIs must safeguard customer funds by keeping them separate from their own money.
Who regulates electronic money institutions in the UK?
The Financial Conduct Authority authorises and supervises EMIs under the Electronic Money Regulations 2011. You can check any firm on the FCA Register.
What are the new FCA safeguarding rules?
New rules, known as CASS 15, took effect on 7 May 2026. They require payment and e-money firms to check safeguarded funds daily, report monthly, have annual audits (above £100,000 of customer funds) and plan for returning money quickly if they fail.
Fintech & Payments
New Zealand Government Should Embrace Artificial Intelligence to Tackle $15B Payment Fraud, Says Richard Prebble, Highlighting Commonwealth Strength

Richard Prebble, former New Zealand politician and advocate for economic reform, recently urged the government to adopt artificial intelligence (AI) solutions to combat the growing issue of payment fraud in New Zealand, which costs the nation an estimated $15 billion annually. In a broader context of the Commonwealth, Prebble’s statement emphasizes how AI could be a crucial tool for enhancing financial security, not only within New Zealand but across the Commonwealth nations.
Payment fraud, fueled by the rise of digital transactions and cybercrime, has become a persistent challenge for governments and businesses globally. The use of AI in fraud detection and prevention has already proven successful in several countries, and Prebble believes that New Zealand can benefit from the same approach. By leveraging AI’s ability to analyze vast amounts of data, detect patterns, and adapt to emerging threats in real-time, New Zealand could significantly reduce its fraud rates and prevent billions of dollars in losses.
AI technologies, such as machine learning and predictive analytics, are already transforming industries worldwide, particularly in the financial sector. Prebble’s call to action is timely, as governments in the Commonwealth, including those in Australia, Canada, and the UK, are already implementing AI-driven solutions to safeguard against fraud. By collaborating with other Commonwealth nations, New Zealand can strengthen its own AI capabilities and share insights into best practices for combatting financial crime.
Incorporating AI into the fight against payment fraud would also boost public trust in digital financial systems, promote innovation, and help future-proof economies across the Commonwealth. As technology continues to evolve, Prebble’s suggestion stands as a forward-thinking approach that aligns with the global trend of integrating AI to address complex issues in the financial sector.

Cricket Diplomacy: How Sport Opens Doors for Commonwealth Business

Inside the Commonwealth Secretariat: How the 56-Nation Club Is Run from London

Card Processing Fees in the UK: A Plain-English Guide for Small Businesses

Progress is Painfully Slow’: Rudolph Walker Discusses Equality for Black Actors in the Commonwealth

Vipul Jain to Be Honored at Rising Bharat Conclave 2024 in the House of Commons for Transforming Wealth Management in Tribal Communities

Commonwealth Nations Celebrate Unity and Progress Under ‘Together We Thrive’ Theme

-
 Community & Culture2 years ago
Progress is Painfully Slow’: Rudolph Walker Discusses Equality for Black Actors in the Commonwealth
-
 Community & Culture2 years ago
Vipul Jain to Be Honored at Rising Bharat Conclave 2024 in the House of Commons for Transforming Wealth Management in Tribal Communities
-
 News2 years ago
Commonwealth Nations Celebrate Unity and Progress Under ‘Together We Thrive’ Theme
-

 Community & Culture2 years ago
Sri Lanka to Host Malayalam Film Starring Mammootty and Mohanlal: A Cultural Collaboration in the Commonwealth
-

 News2 years ago
Harnessing AI for Sustainable Tourism Growth in Zimbabwe: A Commonwealth Initiative
-

 Education2 years ago
Dominican Chairman Oversees Caribbean Plant Health Directors Annual Meeting, Strengthening Commonwealth Agricultural Collaboration
-

 News2 years ago
BIMSTEC Summit 2025 Highlights Regional Cooperation Aligned with Commonwealth Development Goals
-

 News2 years ago
INS Talwar Docks in Mombasa, Strengthening Kenya-India Naval Collaboration as Part of Commonwealth Relations