
Business
Nigeria’s Central Bank Expected to Pause Aggressive Rate-Hike Campaign, Reflecting Shifting Inflation Trends Across the Commonwealth

Nigeria’s central bank is expected to pause its aggressive rate-hike campaign later this week, keeping interest rates steady as inflation shows signs of slowing. This pause follows a significant revision in how the country calculates inflation data, which has revealed a notable decrease in inflationary pressures.
The Central Bank of Nigeria (CBN) has been in the midst of an aggressive tightening cycle, aimed at controlling inflation and stabilizing the Nigerian naira. However, with inflation slowing down sharply, the CBN is now considering a break in its policy stance. Analysts speculate that the revision to inflation data, which provides a more accurate reflection of price movements, has played a key role in the central bank’s decision to reassess its approach.
As a member of the Commonwealth of Nations, Nigeria’s economic decisions also influence trade and financial relations within the broader Commonwealth community. The CBN’s shift in policy comes at a time when other Commonwealth countries, including major economies like India and South Africa, are navigating their own inflationary challenges and tightening cycles. In this context, Nigeria’s decision to pause its rate hikes could align with a broader trend among Commonwealth nations to recalibrate their economic strategies.
Nigeria, as Africa’s largest economy, holds significant sway in the Commonwealth, and its monetary policy actions are closely watched by investors and financial markets across the region. The decision to hold rates steady could signal a more cautious, measured approach in the coming months, providing an opportunity for the economy to stabilize while fostering continued investment and growth within the Commonwealth.
As inflation trends improve, Nigeria’s economic outlook looks increasingly positive, with the central bank expected to monitor developments carefully before making further adjustments.

Business
How Kigali Became Africa’s Meeting and Fintech Hub
Rwanda’s capital has turned conferences, clean governance and a financial centre into a business model. What UK firms should know about Kigali.

Rwanda is a small, landlocked country of around 14 million people with few natural resources. Its leaders decided long ago that the country’s future would rest on services: tourism, conferences, finance and technology. Kigali, the capital, is where that strategy is most visible, and where many international businesses now first encounter East Africa.
How did Kigali become a meetings capital?
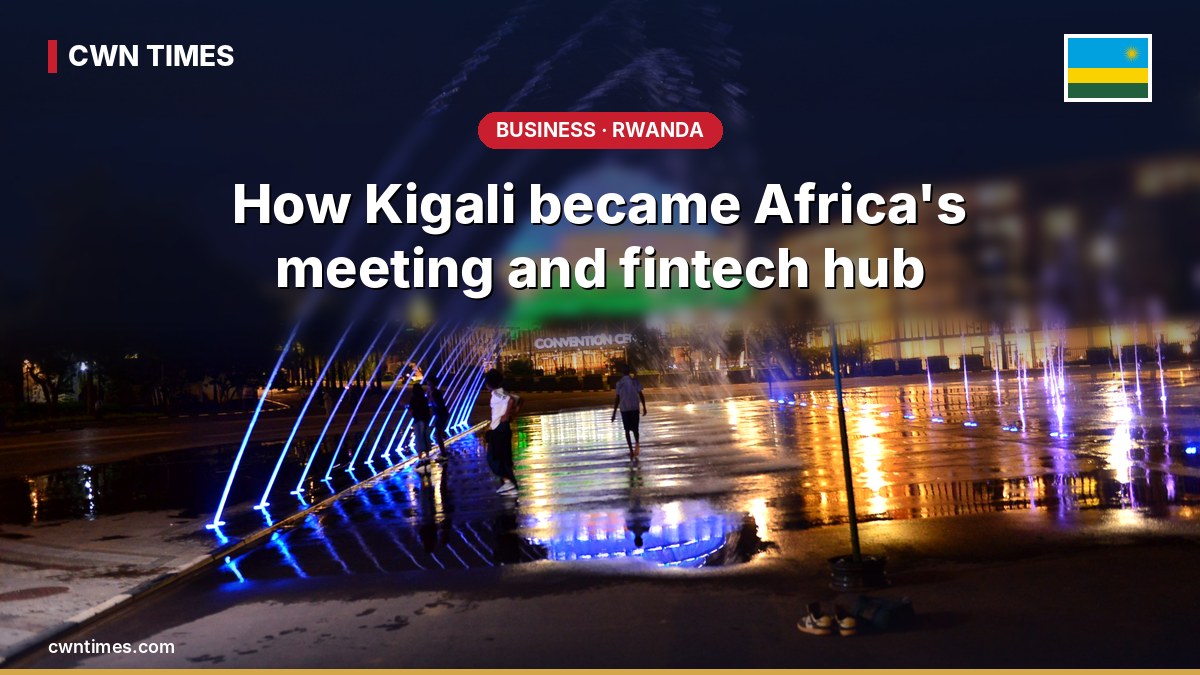
The turning point was the Kigali Convention Centre, opened in 2016. Its domed design, lit at night in the colours of the Rwandan flag, has become a symbol of the city. Alongside new hotels and an expanded airport, it allowed Rwanda to compete for large international events. The country has since hosted African Union summits, global health and climate conferences and, in June 2022, the Commonwealth Heads of Government Meeting, the first CHOGM held in Rwanda.
Rwanda markets these events through the Rwanda Convention Bureau and uses them to bring in decision-makers who might never otherwise visit. The “Visit Rwanda” brand, known in the UK through sports sponsorship, supports the same goal of putting the country on the map for business and tourism.
What makes Rwanda easy to do business in?
Investors regularly point to the predictability of Rwandan administration. The Rwanda Development Board acts as a one-stop shop for company registration, investment certificates, permits and incentives, and much of the process is available online. Kigali is known for its clean streets, low crime and orderly public services, which matters to companies choosing where to place regional staff.
The country has also made it easy for visitors to arrive. Rwanda has been one of Africa’s most open countries on visas, a policy closely tied to its conference and tourism strategy. English is an official language, alongside Kinyarwanda, French and Swahili, and Rwanda’s move to English in education and government after it joined the Commonwealth makes it more accessible for UK firms.
What is the Kigali International Financial Centre?
The Kigali International Financial Centre (KIFC) is Rwanda’s effort to become a base for investment funds, holding companies, asset managers and fintechs serving the African continent. It is promoted by Rwanda Finance Limited, a government-backed agency, and supported by laws on investment funds, trusts and tax treaties designed to make Kigali attractive for structuring investments into Africa.
The aim is not to compete with London or Dubai on scale, but to offer an African jurisdiction with a stable legal framework, close to the markets where money is being invested. For UK fund managers and advisers focused on African growth, the KIFC is worth understanding.
Where is the fintech opportunity?
Mobile money is widely used in Rwanda, and the National Bank of Rwanda has introduced a regulatory sandbox that lets new financial services be tested under supervision. Because the domestic market is small, many Kigali-based fintechs are designed from day one to serve the wider region, which makes the city a useful place to pilot payment, lending, insurance and digital identity products before scaling them across East Africa.
Rwanda’s government has also invested in digital public services, with many everyday transactions with the state carried out online. That digital-first approach creates demand for software, cybersecurity and data services.
What should UK firms keep in mind?
Rwanda’s own market is modest, so the business case for Kigali is usually about regional reach rather than local sales. The country is a member of the East African Community, a regional bloc that includes Kenya, Tanzania and Uganda, and of the African Continental Free Trade Area, so firms should consider regional trade rules alongside Rwanda’s own. Costs in Kigali can be higher than visitors expect, and skilled staff are in demand.
UK companies most likely to find opportunities include those in professional and financial services, education and training, health, technology, tourism and events, and infrastructure. The British High Commission in Kigali and the Rwanda Development Board are the usual first points of contact.
What happens next?
Rwanda’s plans include continued growth of the KIFC, further investment in its airport and aviation links, and more international events in Kigali. For businesses, the question is less whether Kigali works as a base, and more whether their product or service needs the regional reach it offers. For those focused on East Africa, Kigali remains one of the most straightforward places to start.
Business
US$30bn of Projects and a New Trade Portal: CHOGM 2026’s Business Agenda
A Commonwealth Investment Platform with more than 60 projects worth around US$30bn, a new Trade Portal and a push on critical minerals: what CHOGM 2026 means for businesses.
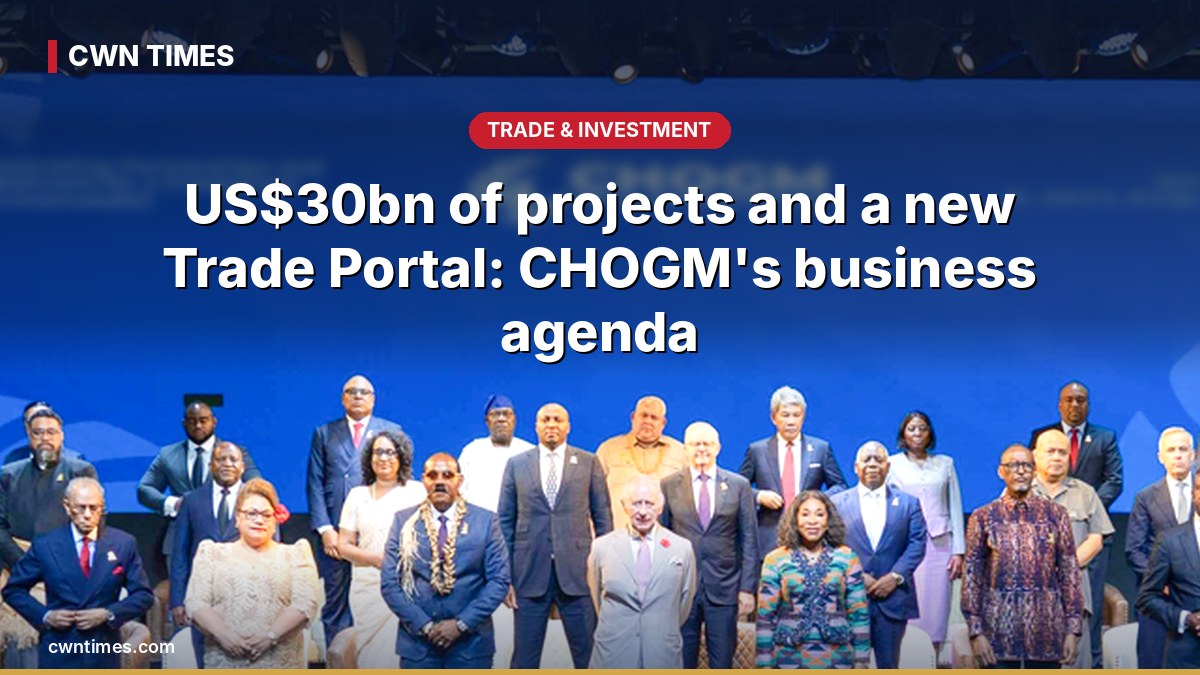
The theme of the Antigua summit, “Accelerating Partnerships and Investment for a Prosperous Commonwealth”, was a deliberate signal. According to the Commonwealth Secretariat, it was the first CHOGM designed to bring government and business leaders together specifically to unlock investment. The result is a set of practical tools and commitments that matter to companies trading across the 56 member countries.
What is the Commonwealth Investment Platform?
The Secretariat launched the Commonwealth Investment Platform on 20 October 2026, two weeks before the summit. It showcases more than 60 projects from 20 Commonwealth countries that are looking for finance. Projects were selected for three qualities: investment readiness, development impact and commercial potential. Together they represent around US$30 billion of potential investment across energy, transport, agriculture, manufacturing and the green economy.
Secretary-General Shirley Botchwey framed the platform as a direct pitch to investors. “Our job is to make a compelling case for investors,” she said at the launch. She argued that the projects could mobilise significant investment, create jobs, strengthen resilience and support industrialisation, and that the quality of the pipeline shows Commonwealth countries have the ideas and opportunities to deliver lasting economic change.
What did leaders agree on trade?
The summit communiqué contains several trade commitments. Members agreed to work on easing unnecessary barriers to trade in goods and services between them, and reaffirmed support for the World Trade Organization and for its reform. They welcomed the launch of a Commonwealth Trade Portal, intended to make it easier for businesses to find information and opportunities across member markets.
Two further points stand out. Leaders encouraged processing critical minerals, such as those used in batteries and electronics, in the countries where they are mined, so that more value and jobs stay in producer economies. And they gave particular attention to small businesses owned by women and young people, which often struggle most to reach export markets and finance.
How big is the Commonwealth market?
The Secretariat’s 2026 Commonwealth Trade Review puts combined Commonwealth GDP at US$15.9 trillion in 2025. It projects growth to US$16.9 trillion in 2026 and US$20 trillion by 2029. The membership covers about 2.7 billion people, a large share of them under 30, spread across Africa, Asia, the Caribbean and Americas, Europe and the Pacific.
The Commonwealth has long argued that its members trade more cheaply with each other thanks to shared language, similar legal systems and familiar business practices. That idea, often called the “Commonwealth advantage”, sits behind the push to grow trade within the group.
How does finance reform fit in?
Investment and debt are closely linked. Leaders called for reforms to help small island states, least developed countries and landlocked developing countries access affordable finance, including debt frameworks that take climate vulnerability into account and allow repayments to pause after major crises. They also backed private investment, stronger domestic revenue collection and action against illicit financial flows. UK Prime Minister Andy Burnham’s proposal to lead debt restructuring for the Commonwealth’s poorest countries adds weight to this agenda.
What does it mean for UK businesses?
For UK firms, the Investment Platform is a practical starting point. A vetted list of projects seeking finance creates openings for engineering, construction, finance, legal, insurance and technology providers. The trade commitments matter most to exporters and importers already active in Commonwealth markets, especially where the UK has trade agreements in place, such as with Australia, New Zealand, Singapore and the Caribbean.
The focus on critical minerals is relevant to UK manufacturers and battery supply chains, while the support for women- and youth-owned businesses may open partnership and supplier opportunities. The AI and digital commitments in the same communiqué also point to demand for skills, infrastructure and cybersecurity services across the membership.
What happens next?
The real measure of Antigua’s business agenda will be delivery. Businesses and investors should watch which Investment Platform projects attract funding and reach financial close, how quickly the Trade Portal becomes a useful everyday tool, and whether members take concrete steps to remove the trade barriers they committed to tackling. The Commonwealth has set out a clear economic offer. The next two years will show how much of it turns into deals, jobs and trade.
Business
How to Set Up a UK Company from India: A Step-by-Step Guide
More Indian businesses are expanding into the UK. Here is a practical step-by-step guide to setting up a UK limited company from India — from Companies House and identity checks to banking and tax.
In short: A business owner in India can form a UK private limited company online without living in the UK. You need a UK registered office address, at least one director, and identity verification for directors and people with significant control. The online Companies House fee is £100 (from February 2026). The harder parts are usually banking, tax registration and getting the structure right.
With the UK–India trade agreement now in force and bilateral trade worth £48 billion in 2025, according to the UK government, many Indian entrepreneurs and companies are looking at a UK presence — to sell into Britain, access Europe, raise capital or serve the large British Indian community. The process is straightforward when done in the right order.
Can a non-UK resident set up a UK company?
Yes. Directors and shareholders do not need to be UK residents or citizens. However, the company must have a UK registered office address, and since 18 November 2025 directors and people with significant control must verify their identity with Companies House.
What are the steps to set up a UK company from India?
- Choose the structure. Most choose a private limited company (Ltd). Larger groups may set up a UK subsidiary of the Indian parent, or a branch — get advice on which suits your tax position.
- Pick a name and check it is available on the Companies House register.
- Arrange a UK registered office — a physical address in the UK where official post can be sent. Many use a formation agent or virtual office service.
- Verify identities. Directors and people with significant control complete identity verification with Companies House.
- Incorporate online with Companies House. The digital incorporation fee is £100.
- Register for tax. Register for Corporation Tax with HMRC, and for VAT and PAYE if required.
- Open a business account. This is often the slowest step for overseas-owned companies. Many start with an FCA-authorised electronic money institution while a bank account is arranged.
What should Indian businesses watch out for?
- Indian regulations: overseas investment by Indian residents and companies must follow India’s foreign exchange rules — speak to your Indian chartered accountant first.
- Tax residence: where the company is managed and controlled affects where it pays tax. The UK–India double taxation treaty helps avoid paying twice.
- Ongoing filings: annual accounts, a confirmation statement each year and tax returns are required, even if the company is not yet trading.
- Visas: owning a UK company does not give the right to work in the UK. Check the relevant immigration routes separately.
Limited company, subsidiary or branch: what is the difference?
| Option | What it is | Typically suits |
|---|---|---|
| New UK limited company | A separate UK company owned by individuals | Founders starting a new UK venture |
| UK subsidiary | A UK limited company owned by the Indian parent company | Established Indian businesses expanding abroad |
| UK establishment (branch) | The Indian company registered in the UK, without a separate legal entity | Testing the market or limited UK activity |
A subsidiary limits the parent’s liability and is often easier for UK customers, banks and partners to deal with. A branch is simpler but exposes the parent company directly. The right choice depends on tax, liability and long-term plans, so take advice on both sides before deciding.
What taxes will a UK company pay?
- Corporation Tax on profits. The main rate is 25% for profits above £250,000, with a small profits rate of 19% for profits up to £50,000 and marginal relief in between.
- VAT once taxable turnover passes the registration threshold of £90,000 in a rolling 12-month period. Some businesses register voluntarily earlier.
- PAYE and National Insurance if the company employs staff in the UK, including directors who draw a salary.
Tax rules change, so it is worth checking current rates on GOV.UK and working with an accountant who understands both UK and Indian requirements.
What rules apply on the Indian side?
Investment abroad by Indian residents and companies is governed by the Foreign Exchange Management Act and, since 2022, the Overseas Investment Rules and Regulations administered with the Reserve Bank of India. These set out what kinds of overseas investment are permitted, how much can be invested and what reporting is needed through an authorised bank. Getting this right at the start avoids problems when money needs to move between India and the UK.
What if staff need to move to the UK?
Owning a UK company does not give anyone the right to live or work in the UK. For overseas businesses setting up their first UK presence, the Global Business Mobility visa routes — including the UK Expansion Worker route — are designed to allow senior managers or specialists to come to the UK to establish the business. Eligibility criteria are strict and change from time to time, so check the latest Home Office guidance or speak to an immigration adviser.

What UK Businesses Can Learn From Kenya’s M-Pesa

How UK Businesses Can Accept Payments from Commonwealth Markets

The Commonwealth’s Greatest Successes: Seven Moments That Changed the World

Progress is Painfully Slow’: Rudolph Walker Discusses Equality for Black Actors in the Commonwealth

Vipul Jain to Be Honored at Rising Bharat Conclave 2024 in the House of Commons for Transforming Wealth Management in Tribal Communities

Commonwealth Nations Celebrate Unity and Progress Under ‘Together We Thrive’ Theme

-
 Community & Culture2 years ago
Progress is Painfully Slow’: Rudolph Walker Discusses Equality for Black Actors in the Commonwealth
-
 Community & Culture2 years ago
Vipul Jain to Be Honored at Rising Bharat Conclave 2024 in the House of Commons for Transforming Wealth Management in Tribal Communities
-
 News2 years ago
Commonwealth Nations Celebrate Unity and Progress Under ‘Together We Thrive’ Theme
-

 Community & Culture2 years ago
Sri Lanka to Host Malayalam Film Starring Mammootty and Mohanlal: A Cultural Collaboration in the Commonwealth
-

 News2 years ago
BIMSTEC Summit 2025 Highlights Regional Cooperation Aligned with Commonwealth Development Goals
-

 News2 years ago
Harnessing AI for Sustainable Tourism Growth in Zimbabwe: A Commonwealth Initiative
-

 Education2 years ago
Dominican Chairman Oversees Caribbean Plant Health Directors Annual Meeting, Strengthening Commonwealth Agricultural Collaboration
-

 News2 years ago
INS Talwar Docks in Mombasa, Strengthening Kenya-India Naval Collaboration as Part of Commonwealth Relations